When the first check has to happen before credit opens
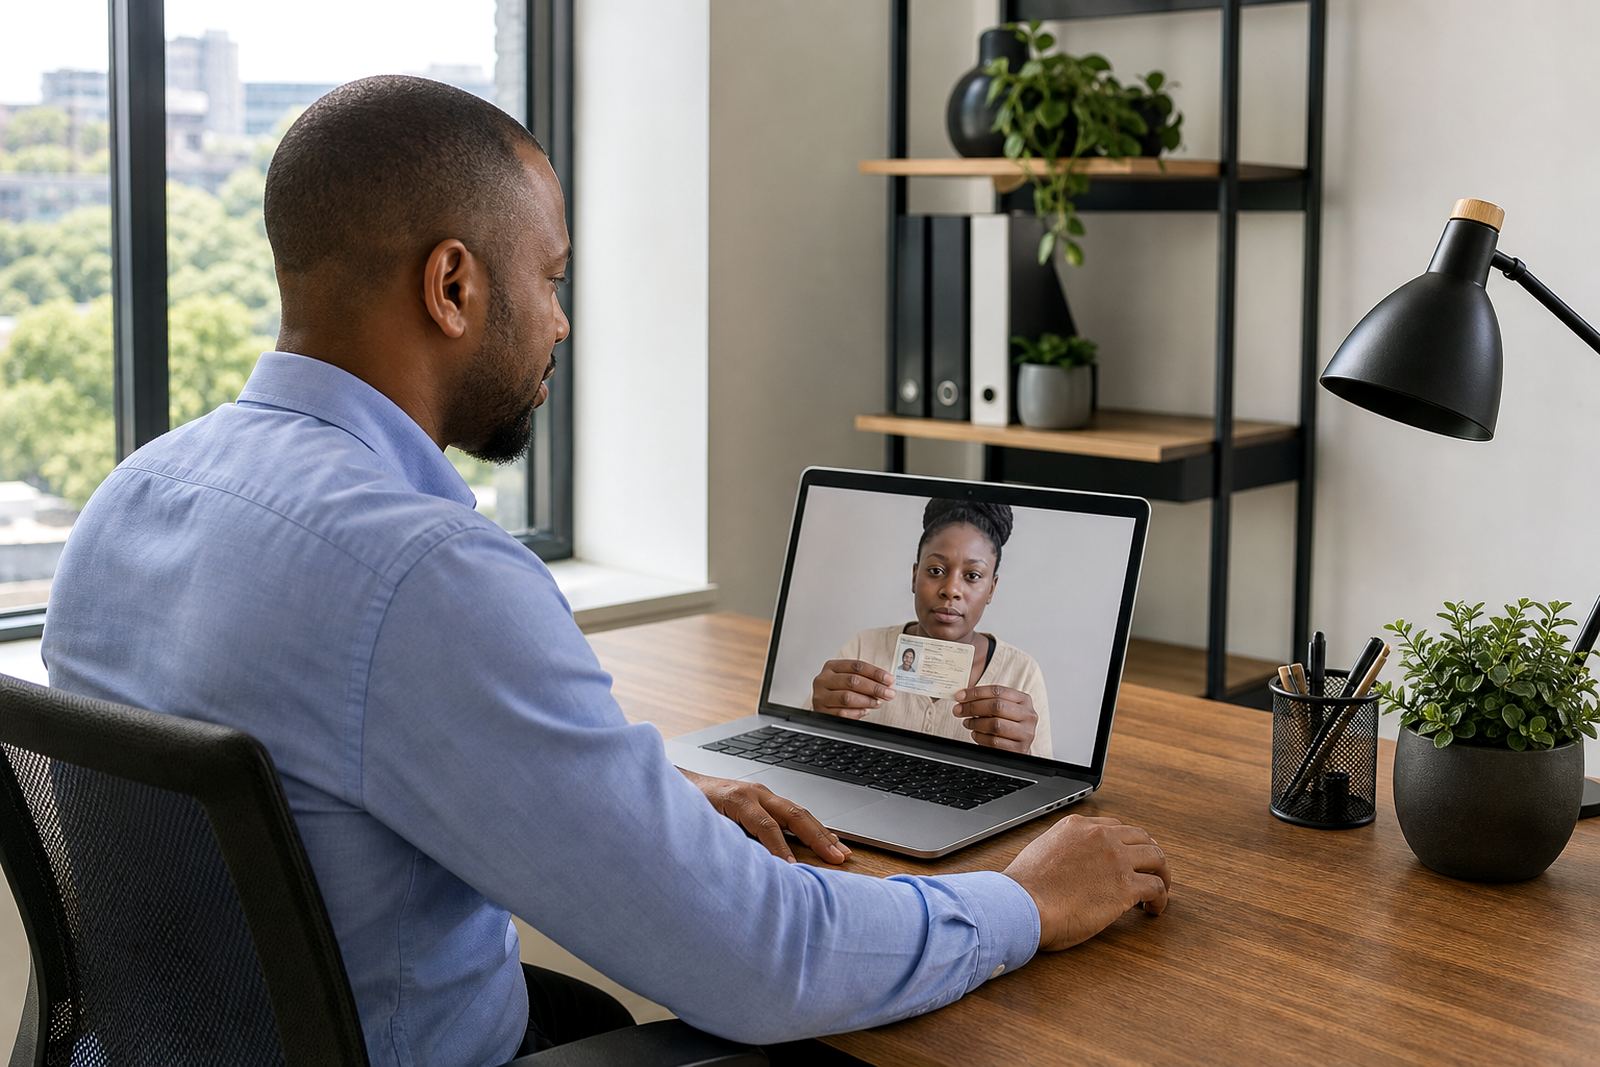
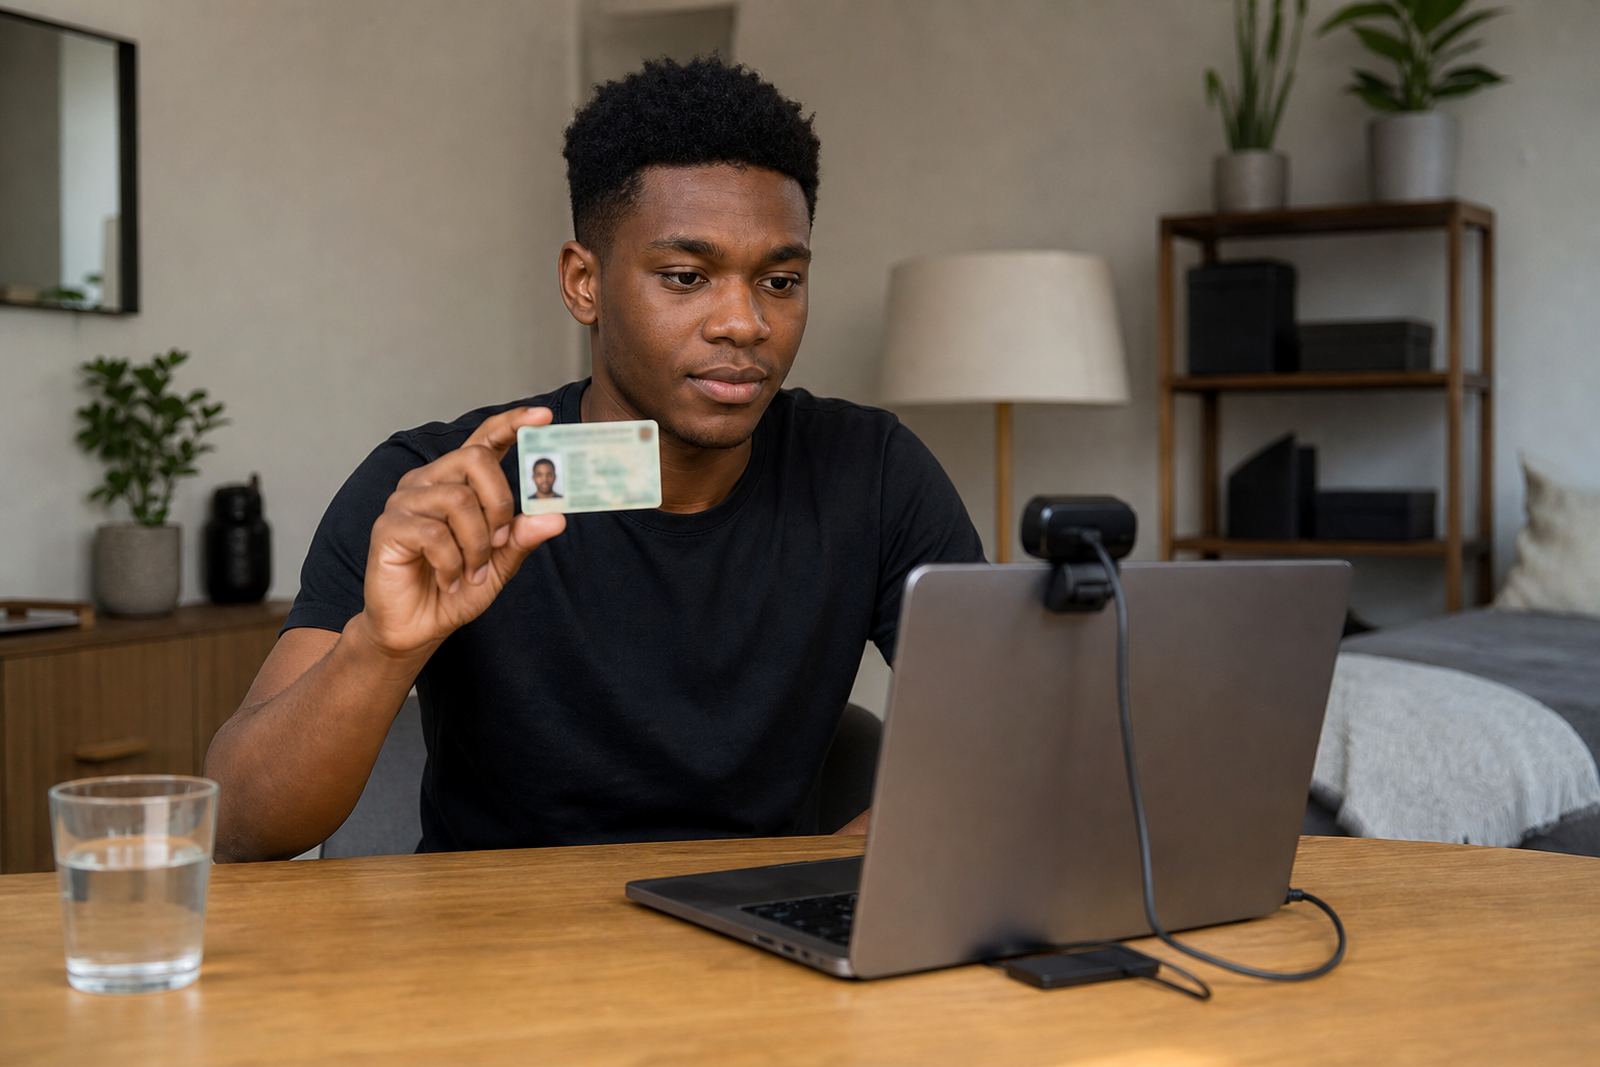
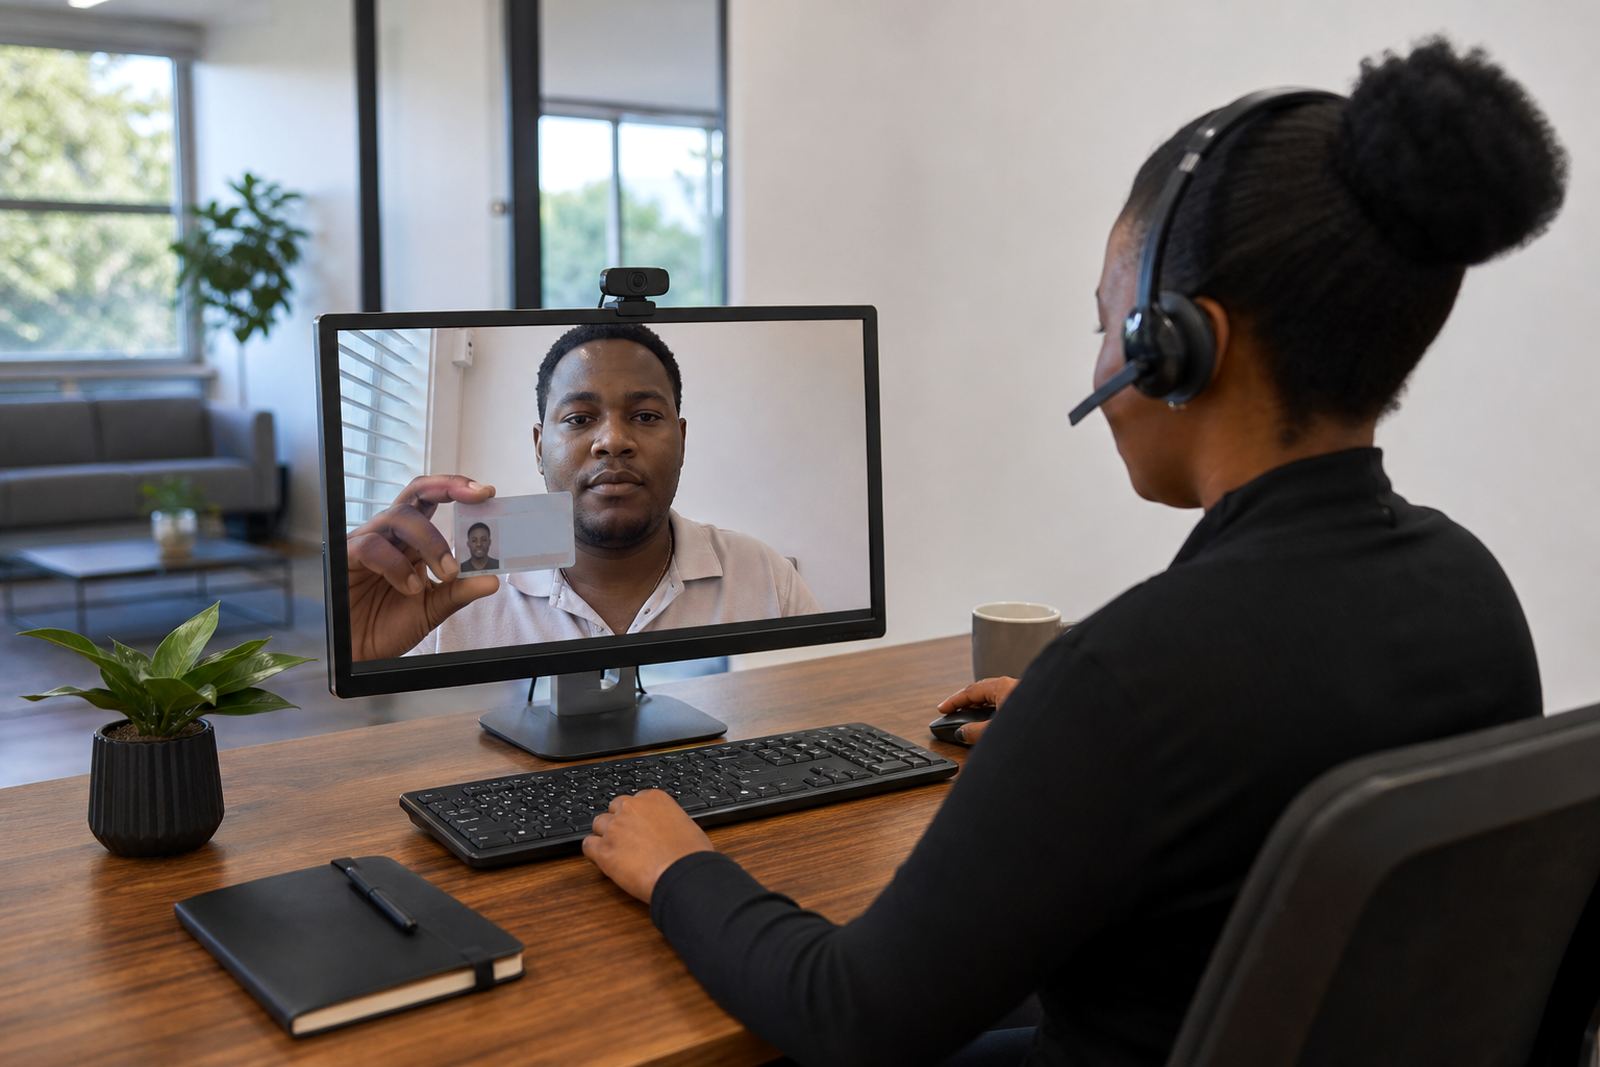
Retail finance teams often need a stronger front gate than a basic online form. A guided video session lets a customer show an ID document, confirm their identity, and complete a live face check before the account moves into credit-linked use.
That works well where the application starts on a laptop or phone and the decision still needs human review. It also suits groups with branch footprints in Johannesburg, Pretoria, Cape Town, Durban and Gqeberha, where central control matters but the customer should not be asked to travel unless the case truly needs it.
- Customer joins a short scheduled or on-demand session.
- Agent views the document, the face and the live interaction.
- Records are stored with consent and internal audit needs in mind.
What the video room needs to do its job
The kit is usually modest. A stable webcam, a clear microphone, a screened operator position and a secure internet connection are enough for the agent side. On the customer side, most sessions only need a phone or computer with a camera, plus a well lit room and a clean background.
Retail finance workflows benefit from a fixed layout that keeps the operator calm and the process repeatable. The screen should give the agent space for the live call, the ID image, notes and escalation prompts without forcing them to hop between five windows. That reduces missed details when names, photos or document features do not line up cleanly.
- One monitor can work for a low volume team, but two screens are easier for sustained review.
- A headset cuts down on noise from nearby counters and passing staff.
- Document capture tools should allow zooming and a second look at edge details.
- Clear light matters more than a fancy camera, especially for older ID documents.
Planning the flow around a retail credit decision
The best setup starts with the business rule, not the software. Decide where the video step sits in the application chain, which cases must go through a live agent, and which items trigger escalation. A simple flow might send standard retail finance applications through a short video check, then route uncertain cases to a second review before approval.
PersonVideo ID works on workflow mapping, integration planning and API coordination so the video step fits the account-opening system already in use. Staff training then covers the wording, the timing of prompts, what to do when the ID image is blurred, and how to keep the tone steady without sounding robotic.
- Set the customer journey before the first pilot starts.
- Write the script to match your credit policy and internal controls.
- Decide who handles exceptions, repeat captures and incomplete sessions.
Common mistakes that slow the handover to credit
Retail finance teams sometimes treat the video step as a loose call rather than a controlled identity check. That leads to rushed questions, poor image capture and weak notes. Another common issue is leaving the agent without a clear escalation path, so borderline cases sit unfinished while the customer is still waiting in the system.
It also helps to avoid overloading the session with extra chatter. The purpose is to verify the person, the document and the live presence, not to bury the customer under a long script. When the process is too wordy, the team starts missing small details like mismatched initials, signs of poor lighting or a face that does not match the document photo.
- Do not let the agent improvise the verification order.
- Do not store weak captures and call them complete.
- Do not skip quality checks after pilot sessions.
Budget ranges that make sense for a South African rollout
Budget usually depends on volume, integration depth and how much operational support the team wants during launch. A smaller retail finance pilot with few seats, simple workflow setup and staff training can fall into the lower tens of thousands of Rand. A broader multi-site rollout with API coordination, refresh training, monitoring and escalation design will move higher, especially where several business units need the same process.
For planning, it is safer to budget in layers: pilot setup, integration work, training, then ongoing operational support. That makes it easier to compare a light-touch roll-out with a fuller managed process. Retail finance teams often find the real cost is not the video session itself but the time spent on exceptions, change requests and rework if the first flow is too loose.
- Lower budgets suit one product line or a narrow pilot group.
- Mid-range budgets suit several teams and a firmer script structure.
- Higher budgets suit multi-branch governance, monitoring and change control.
How PersonVideo ID supports the operating side
PersonVideo ID operates from Rosebank, Johannesburg, with support for clients across Johannesburg, Pretoria, Cape Town, Durban and Gqeberha. The team works on pilot launch support, operational reporting, quality monitoring, refresh training and go live stabilising where a retail finance process needs a firmer hand after launch.
That mix matters when the account opening counter, the risk team and the operations group all need the same session to mean the same thing. One person may want smoother scripting, another may want stronger escalation design, and another may want cleaner reporting. The service is shaped around those moving parts, not around a one-size setup.
Clients contact us through our contact form on our contact page when they want to plan the flow, shape the script and align the integration work. The practical aim is a session that fits the retail credit journey and does not create extra friction for the customer or the back office.