When a loan application needs stronger proofing
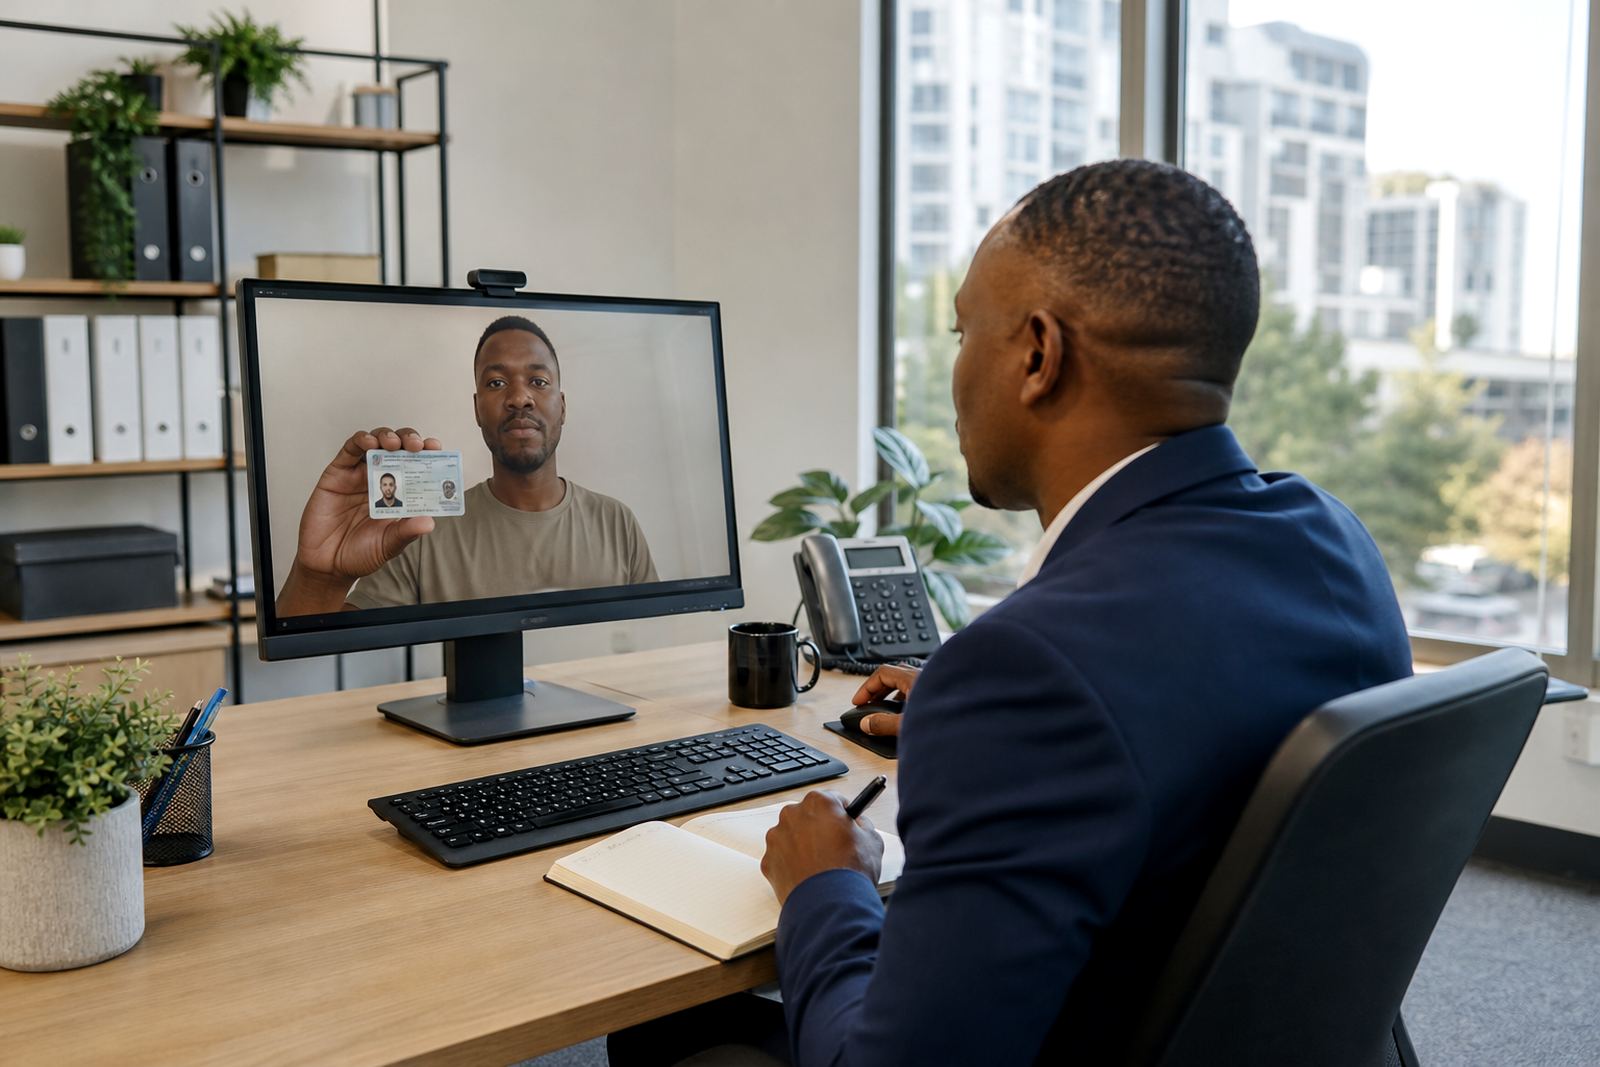
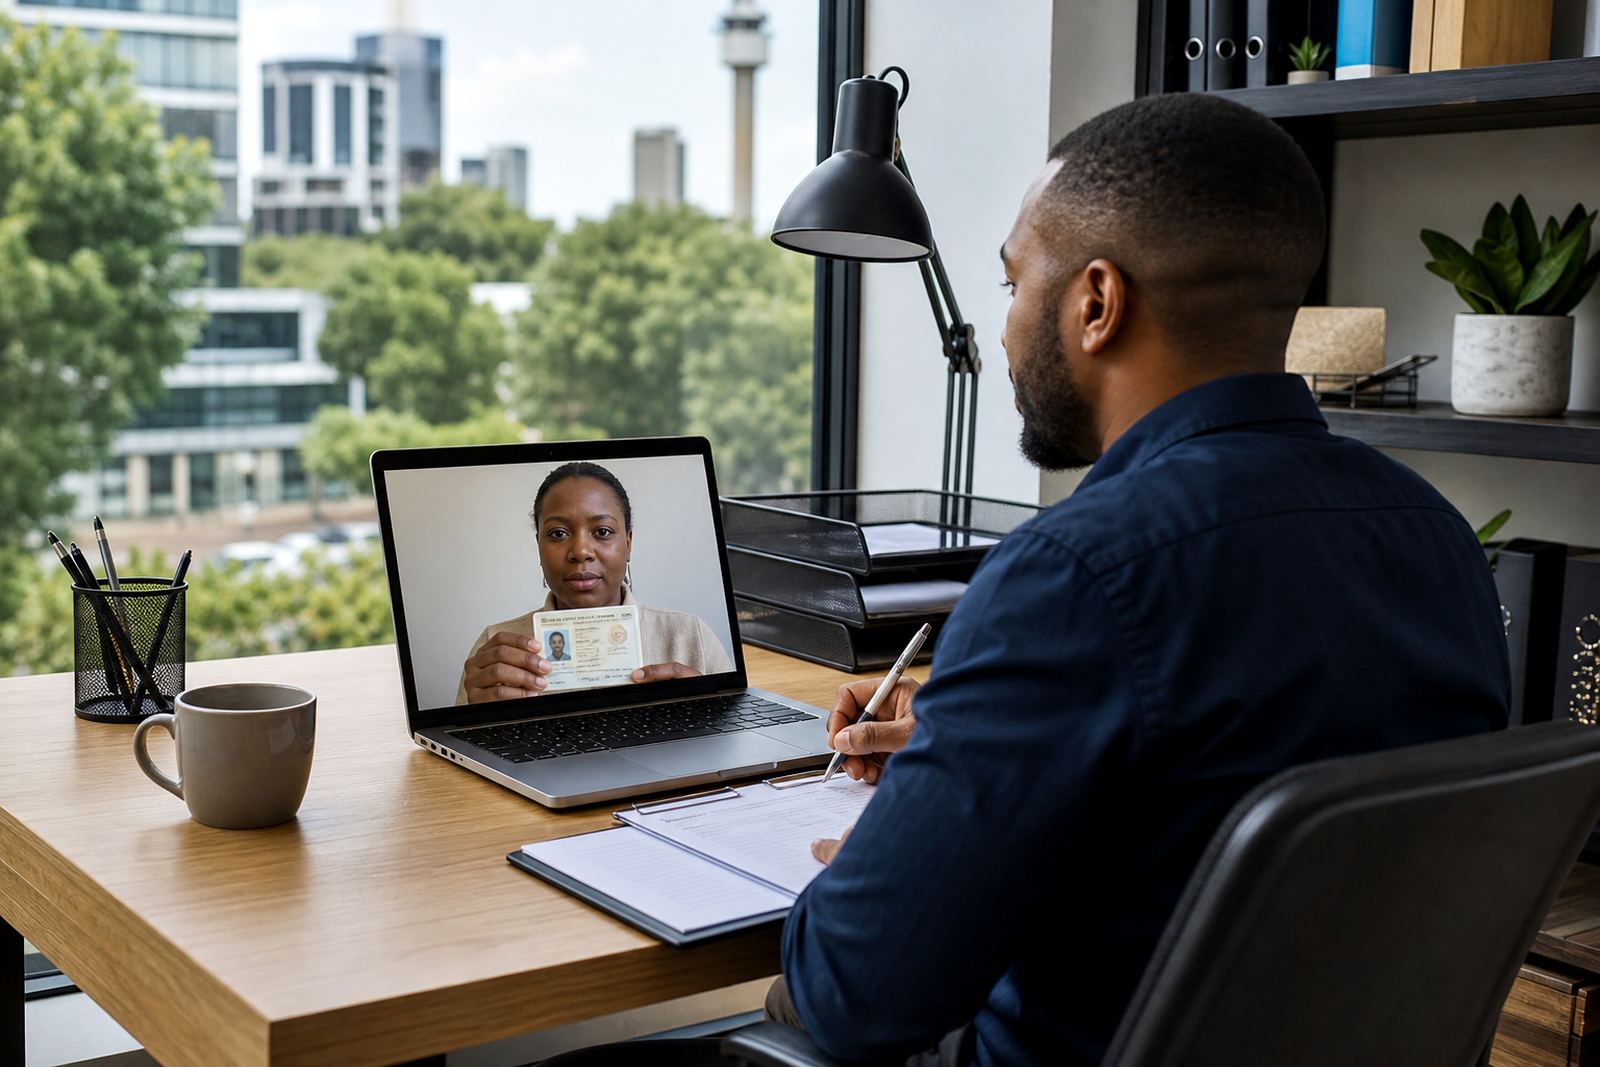
Online lenders often deal with applicants who move between phones, laptops and branches, so the identity step has to hold up across different conditions. A short guided video session gives the applicant a clear sequence: show the ID document, let the agent check the face, and capture the details needed for internal due diligence and record keeping. That is useful when the client has no branch visit, or when a branch exists but the applicant still prefers digital onboarding.
For lending teams, the main pressure is not just fraud. It is also poor image quality, rushed document handling and inconsistent agent wording. A steady process reduces those gaps. It also helps when a lender operates across Johannesburg, Pretoria, Cape Town, Durban and Gqeberha, where teams often need the same verification standard even if their sales and credit processes differ.
A typical setup for remote video verification
The equipment set is usually straightforward. The applicant uses a phone or laptop with a camera, microphone and a stable data connection. On the lender side, trained verification agents work from a controlled setup with secure video access, screen access for case notes and a process for storing the session record where required. Some lenders also want integration into their onboarding system so that a case cannot move forward until the verification result is logged.
- Device camera for live face capture and document viewing
- Microphone and audio path for guided instructions
- Secure session link or embedded video flow
- Case management screen for notes, flags and outcomes
- Record retention controls aligned to internal policy
Where the lender already has a digital application form, the verification step should sit close to the rest of the journey. If it feels detached, applicants drop off or staff start patching the process with manual workarounds.
How the workflow is usually laid out
A lending flow works best when the verification step is planned before launch, not after the first pile of flagged cases arrives. Workflow Mapping and Integration Planning help define where the customer enters, where the session starts, what the agent sees and what must happen after the check is complete. API Coordination matters when the lender wants the verification result to update the account record, risk queue or onboarding dashboard without extra manual entry.
We also plan the operational side. That means script wording, escalation points, and what the agent does when the document is blurred or the applicant keeps moving out of frame. Pilot Launch Support is useful here because it shows where the process breaks under normal use, not just in a neat test run. Change Request Support and Go Live Stabilising matter when a lender adjusts product rules, age checks or document handling after launch.
Training the people who will run the checks
Even a good verification platform can drift if staff are not trained to use it the same way. Lending teams usually need practical coaching on document prompts, liveness cues, matching the person to the ID and keeping the tone calm without sounding scripted. Agent Script Design and Staff Training help set that pattern, while Refresh Training gives the team a chance to reset when process changes start to creep in.
- How to guide the customer through ID display without rushing
- What to note when the face match is unclear
- When to escalate to a senior verifier
- How to keep records tidy for internal review
- How to handle repeat issues without changing the standard
Quality Monitoring matters in this kind of environment because one weak session can create a support issue later. A lender wants consistency, not clever shortcuts.
Common mistakes lenders make with video KYC
One common mistake is treating the verification step like a narrow tech task. In practice, it affects onboarding rates, exception handling, audit trails and customer service. Another mistake is asking agents to improvise when the applicant has poor lighting or the ID document is worn. That creates uneven decisions and awkward rework.
Some lenders also underplan for staff handover. If one team understands the workflow and another only knows the button clicks, the process frays when volumes shift. Escalation Design should cover document issues, identity mismatches and failed sessions. Operational Reporting then gives managers a clear view of where the process is getting stuck, which is more useful than guessing from a few unhappy cases.
A smaller but serious issue is unclear record keeping. A video verification session is only useful if the lender can show what was checked, what was captured and how the outcome was stored. That is where internal policy and POPIA aware handling need to sit inside the process, not beside it.
Budget ranges that make sense in rand terms
For a South African lending platform, budget depends on how many sessions you expect, how much integration work is needed and whether the lender wants training and reporting wrapped into the rollout. A small pilot with limited workflow mapping and basic staff training might start around R45,000 to R95,000, depending on scope and the number of decision points. A larger launch with API alignment, script planning, escalation rules and pilot support can land between R120,000 and R280,000.
Monthly operating costs are usually shaped by session volume, review depth and any ongoing refresh training or change support. Lenders that want steady oversight, reporting and queue management should budget for that too, not only for the first launch. The main saving comes from fewer manual corrections and fewer cases that have to be chased through a second process.
If the lender operates across multiple provinces, costs can rise where internal teams need more training or where different product lines need separate verification rules. That is normal. It is better to price the workflow properly than to bolt pieces on later.
What lending teams usually ask us to cover
Our Johannesburg base supports lenders across South Africa with the practical side of remote verification. That often includes setup decisions, operational rules and the people side of the rollout. The work can be shaped for new credit products, digital account opening or a tighter proofing step for higher risk applicants.
- Workflow Mapping for onboarding journeys
- Integration Planning and API Coordination
- Staff Training and Refresh Training
- Agent Script Design and Escalation Design
- Operational Reporting and Quality Monitoring
- Pilot Launch Support and Go Live Stabilising
For lenders in Rosebank, Sandton or Midrand, the process may sit close to a central operations team. For national lenders, the same structure can still work across branches and remote sign-up channels. The goal is a verification step that feels controlled and clear, without turning the onboarding counter into a bottleneck.